Why QuickBooks® reconciliation keeps failing.
When reconciliation fails once, you fix it. When it fails every month — the balance won’t tie, prior periods reopen, the difference grows — the cause is systemic, and another adjustment never holds. This is the root-cause view: the process reasons reconciliations fail over time, and the process discipline that makes reconciliation stick.
Call (877) 751-5575. Or book a discovery call.
QuickBooks reconciliation that “keeps failing” isn’t a one-time error — it’s a systemic problem where something in the process re-introduces the same fault every period, so a one-off fix never holds. One root cause is the absence of a regular monthly cadence, which lets skipped months pile up until every error compounds.
Other systemic causes: editing reconciled transactions, forcing balances with adjustment entries that mask real errors, auto-adding bank-feed matches without review, no one owning the close, a wrong opening balance, and mixing personal and business spending. The cure is process — monthly discipline, locked periods, reviewed feeds, and a named owner — not another adjustment.
They took something that felt overwhelming to me as a first-year business owner and made it simple.
What stood out the most was TechBrot Inc’s attention to detail.


Reconciliation that keeps failing: process fix or cleanup.
The systemic causes, the process steps that make reconciliation stick, and the signals that the damage is in the books — set out in full below.
Get the free file review · Cleanup vs reconciliation · Diagnose a reconciliation discrepancy
The systemic causes, one by one.
The process fixes address these in the same order — so working through them in sequence removes the recurring failure at its root, not just for one month.
Cause 01 · There’s no regular reconciliation cadence
When reconciliation isn’t done on a fixed monthly schedule, skipped months pile up — and the more periods that go unreconciled, the harder each one becomes, because errors compound and the source of any difference gets buried under later activity. A book reconciled monthly keeps each period small enough to tie; a book reconciled once a year carries a year of compounded errors into every attempt.
Cause 02 · Reconciled transactions get edited or deleted
Once a period is reconciled, changing a transaction inside it — editing an amount, deleting an entry, changing a date — silently unbalances that month and every month after it. Without locked periods, anyone can reopen a closed month by accident, and the next reconciliation fails for a reason that happened weeks ago.
Cause 03 · Balances get forced with adjustment entries
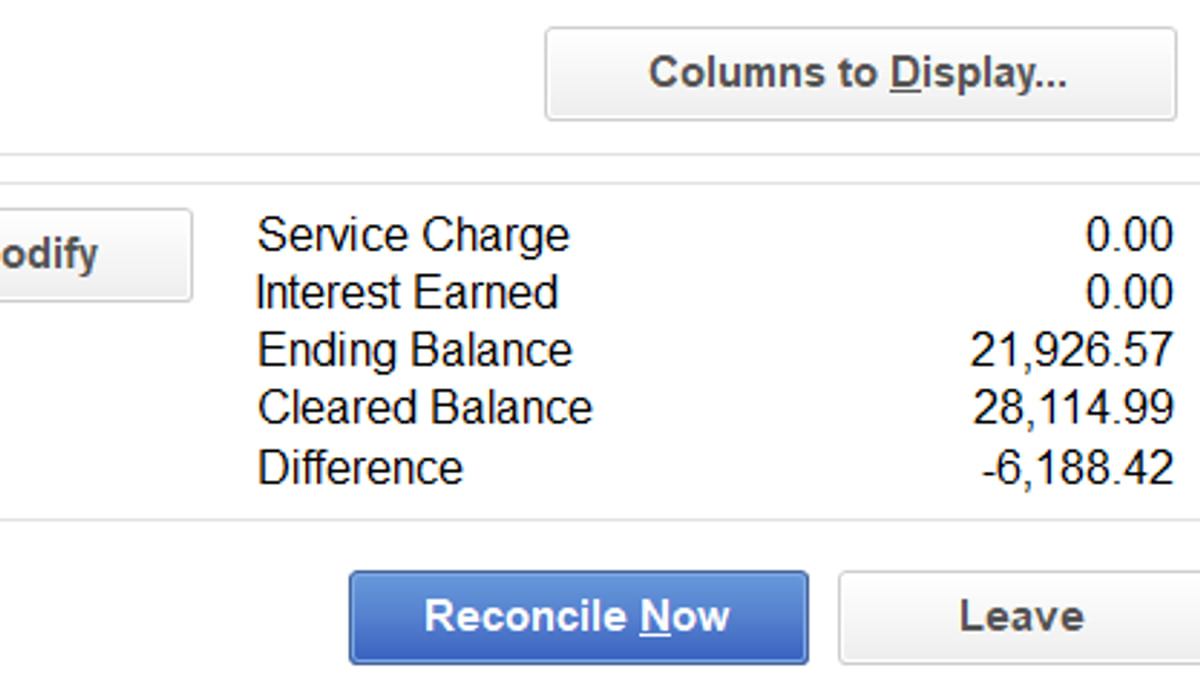
When a reconciliation won’t tie, it’s tempting to let QuickBooks post a reconciliation adjustment to force it to zero. That makes the screen balance but masks the real error — a missing deposit, a duplicate, a wrong amount — which is still in the books. Forced adjustments accumulate, the adjustment account grows, and the books drift further from reality every month.
Cause 04 · Bank-feed transactions are auto-added without review
Bank feeds and auto-add rules are powerful, but accepting matches without reviewing them lets duplicates, miscategorized entries, and wrong matches flow straight into the register. Each one is a future reconciliation difference. The feed isn’t the problem — accepting it unreviewed is.
Cause 05 · No one owns the close
When responsibility for reconciliation is shared or undefined, it falls through the cracks — everyone assumes someone else did it, months slip, and there’s no single person verifying that every account ties. A reconciliation process without a named owner is a process that quietly stops happening.
Cause 06 · Foundational faults: a wrong opening balance, or mixed personal and business spending
Two foundational faults make every reconciliation fail from the start: an opening balance that was never set correctly, so the account can never tie no matter how clean the activity; and personal and business spending run through the same accounts, so the register never matches a clean business statement. Both are structural — the moment a file review is warranted.
How to make reconciliation stick.
Six process steps, in order. This is discipline, not a one-off cleanup — if you work through them and reconciliation still fails every month, the books need a proper repair.
- 1
Set a fixed monthly reconciliation cadence
Pick a date each month — right after statements arrive — and reconcile every bank and credit-card account then, every month, without skipping. A reliable cadence is the foundation: it keeps each period small, catches errors while they’re fresh, and stops months from piling up into a cleanup.
- 2
Lock or close reconciled periods
After a period reconciles, close the books through that date (set a closing date, with a password where available) so reconciled transactions can’t be edited or deleted by accident. Locking the period protects the work you just verified and stops a future month from failing because of a change to a past one.
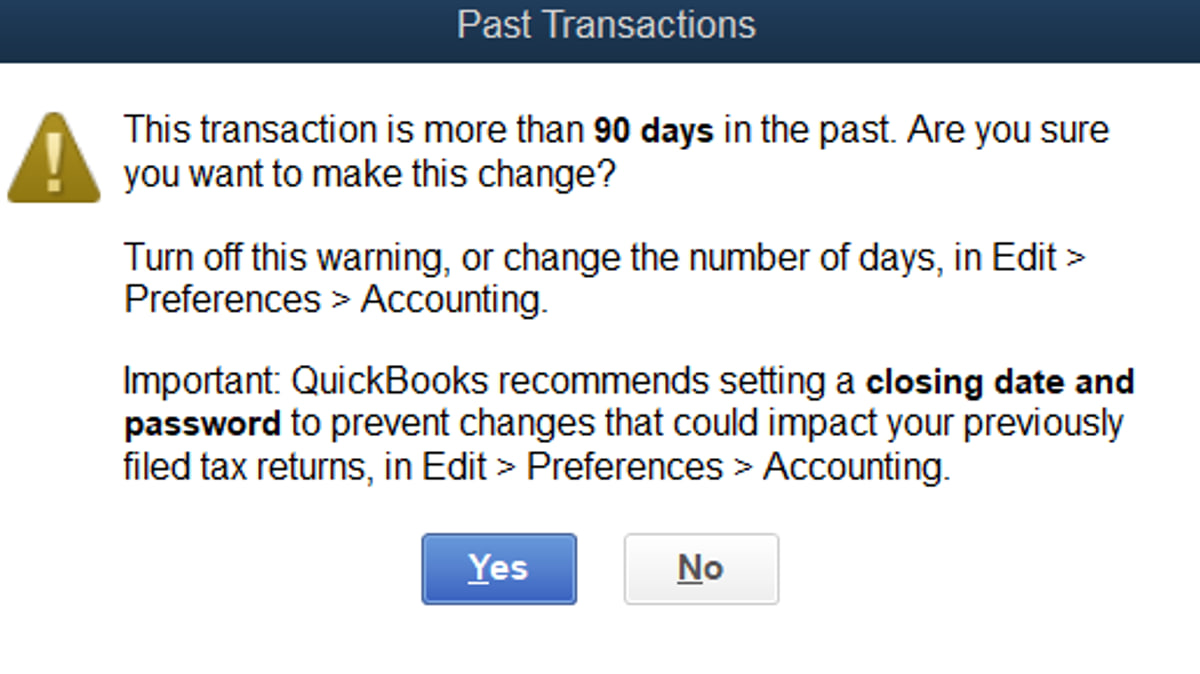
Redacted client file — QuickBooks Desktop’s Past Transactions warning: the change is more than 90 days in the past, and QuickBooks recommends setting a closing date and password. - 3
Review every bank-feed match before accepting it
Treat the feed as a queue to review, not a queue to approve. Before accepting a match or letting a rule auto-add, confirm the amount, the account, and that it isn’t a duplicate of something already entered. Reviewing at intake is far cheaper than untangling bad matches at reconciliation.
- 4
Investigate differences — never force the balance
When a reconciliation won’t tie, find the cause: a missing or duplicate transaction, a wrong amount, an uncleared item, or a timing difference. Do not let an adjustment entry force it to zero except as a deliberate, documented last resort — forcing the balance hides the error and guarantees it returns.
- 5
Assign one clear owner of the close
Name a single person responsible for reconciling every account each month and for confirming the close is complete. Clear ownership is what turns reconciliation from a task that gets skipped into a routine that reliably happens — one accountable owner, a defined checklist, a consistent date.
- 6
Confirm the opening balance is correct — and separate personal spending
Verify the opening balance of each account ties to the bank as of its start date; if it doesn’t, fix the foundation before anything else, because no amount of monthly discipline ties an account that started wrong. And keep personal spending out of business accounts so the register can match a clean business statement. If either fault runs deep, that’s where a file review and cleanup come in.
Three signals it’s a ProAdvisor call.
Forced adjustments have piled up
The reconciliation only ties because adjustment entries keep forcing it — and that adjustment account keeps growing. Each forced balance buried a real error; unwinding them and finding the true differences is cleanup work, not another adjustment.
Reconciled months keep reopening
You reconcile a period, then later it’s out of balance again because transactions inside it were edited or deleted. When months of reconciled work no longer hold, the trail is corrupted and the file needs a proper repair plus locked periods to keep it fixed.
No process change makes it stick
You’ve set a cadence and tried to clean it up, and it still fails every month — a sign of a foundational fault like a wrong opening balance, mixed personal and business activity, or accumulated damage. That’s the moment to have the file assessed before the gap compounds further.
When a failing reconciliation is no longer a software problem.
A reconciliation that keeps failing is rarely a software fault. It is usually the way the books are kept, and fixing that means fixing the books and the routine behind them.
- Forced adjustments have accumulated over several periods.
- Months that were reconciled keep reopening.
- Every process change so far has lasted a month or two.
Start with the free QuickBooks file review — a limited review that identifies likely issues and the information needed for a written scope, with the findings in plain English. If the findings show that the books themselves need work, that is QuickBooks cleanup, quoted as a fixed fee against a written scope before any work starts.
A QuickBooks ProAdvisor fixes the books and the process behind them.
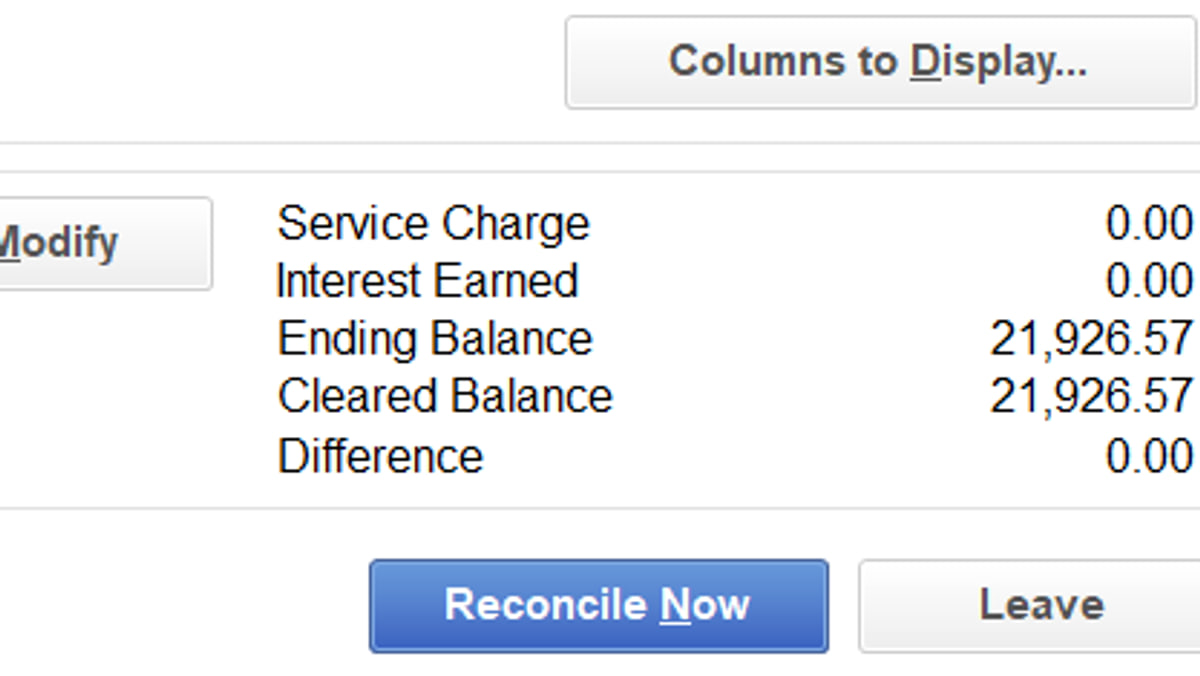
Stopping reconciliation from failing for good is two jobs: repairing the damage already in the books, and building a process so it doesn’t recur. The repair is finding and unwinding the forced adjustments, locating the real differences they hid, correcting a wrong opening balance, and re-running each month until it ties to the statement. The process is everything that keeps it tied afterward — a fixed monthly cadence, locked reconciled periods, reviewed bank feeds, and one accountable owner of the close. A QuickBooks ProAdvisor holding the Intuit QuickBooks Certification Level 2 does both against a written scope.
What people ask about reconciliation that keeps failing.
Why does my QuickBooks reconciliation keep failing every month?
Because the cause is systemic, not a one-off. Common roots: no regular monthly cadence so skipped months pile up; reconciled transactions being edited or deleted; balances forced with adjustment entries that hide the real error; bank-feed matches auto-added without review; no one owning the close; an opening balance that was never set correctly; or personal and business spending mixed in the same accounts. Until the process changes, the same failure returns.
How is this different from “reconciliation is broken” or chasing a discrepancy?
This page is the root-cause, process view of why reconciliation keeps failing over time. If reconciliation is broken right now and you need to triage it, the urgent reconciliation-broken guide is the faster path. If you’re hunting one specific difference — a beginning balance that’s off or a discrepancy report that won’t clear — the discrepancy guide covers diagnosing that single item. Here we cover the systemic reasons and the process fix so it stops recurring.
Should I ever force a reconciliation to balance?
Not as a routine fix. Letting an adjustment entry force the balance to zero makes the screen tie but hides the real error — a missing deposit, a duplicate, a wrong amount — which stays in the books. Forced adjustments accumulate and the books drift from reality. Investigate and fix the actual difference instead; reserve a documented adjustment only for a deliberate, last-resort case you can explain.
How often should I reconcile in QuickBooks?
Every account, every month, on a set date — ideally right after statements arrive. A reliable monthly cadence keeps reconciliation from failing: each period stays small, errors are caught while they’re fresh, and months never pile up into a cleanup. Skipping months is a systemic cause of recurring failure.
Why does editing a reconciled transaction break things later?
Once a period is reconciled, changing a transaction inside it — editing an amount, deleting an entry, or changing a date — silently unbalances that month and every month after. The next reconciliation then fails for a reason that happened weeks ago. The fix is to close or lock reconciled periods so past months can’t be altered by accident.
Does mixing personal and business spending cause reconciliation to fail?
Yes, structurally. When personal and business transactions run through the same accounts, the register can never match a clean business statement, so reconciliation fights itself every month. Keeping personal spending out of business accounts — and confirming the opening balance is correct — removes two foundational faults that make every reconciliation fail from the start.
When should I stop fixing this myself and call a ProAdvisor?
When forced adjustments have piled up, when reconciled months keep reopening because of edits, when the opening balance was wrong from day one, or when no process change makes it hold. That’s accumulated damage a single fix can’t clear. We start with a free file review, then a focused diagnostic is a fixed-fee scope from $450, or a bookkeeping cleanup ($1,200–$15,000+) if the books are behind.